Tom Essaye Quoted in CNBC on May 17, 2019
Tom Essaye quoted in CNBC on May 17, 2019. “Through any lens, this is a broadside against the Chinese government, which is generally considered to be the beneficial…” Click here to read the full article.


Tom Essaye quoted in CNBC on May 17, 2019. “Through any lens, this is a broadside against the Chinese government, which is generally considered to be the beneficial…” Click here to read the full article.
What’s in Today’s Report:
Futures are modestly lower following an uneventful weekend as investors digest Friday’s negative trade headline (that U.S./China trade discussions have been suspended).
On trade, there was no new news over the weekend, but several U.S. tech firms have stopped conducting business with Huawei, per the Commerce Department decision, and that’s just further escalating the U.S./China trade conflict.
Economically, there were no market moving reports (Japanese GDP was stronger than estimates but the details weren’t great).
There are no economic reports today but there are multiple Fed speakers, most important of which is Powell (7:00 p.m. ET), although he’s not expected to make extensive comments on policy. Other Fed speakers today include: Bostic (8:50 a.m. ET), Harker (9:30 a.m. ET), Williams & Clarida (1:00 p.m. ET).
Given the lack of data and important Fed speak, trade headlines should drive markets today and any formal retaliation by China for the Huawei decision will make the trade situation worse, and likely pressure stocks.
Tom Essaye was quoted in Markets Insider on May 15, 2019. The red metal has been the “single-best leading indicator for stocks over the past 18 months,” and is flashing a warning sign for…” Click here to read the full article.
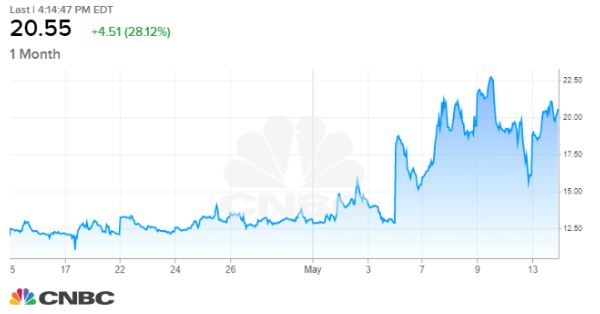
Tom Essaye quoted in CNBC on May 13, 2019. “Volatility surged to multi-month highs last week as US-China trade war drama unexpectedly escalated…” Click here to read the full article.
What’s in Today’s Report:
Futures are modestly weaker following disappointing Chinese economic data. Nothing new happened over night with U.S./China trade.
Chinese Retail Sales (7.2% vs. (E) 8.6%), Fixed Asset Investment (6.1% vs. (E) 6.4%) and Industrial Production (5.4% vs. (E) 6.3%) all missed estimates, implying the Chinese economic recovery might not be as solid as thought.
Today focus will shift back to economic data. The Chinese data was underwhelming and that will put more pressure on today’s U.S. data to reassure markets about growth.
The key reports today (in order of importance) are: Retail Sales (E: 0.2%), Empire State Manufacturing Survey (E: 9.0), Industrial Production (E: 0.0%), Housing Market Index (E: 64). Again, “bad” numbers from these reports that makes the Fed more dovish may cause a temporary bounce in stocks, but that’s not good for stocks in the medium/longer term.
Finally, there are two Fed Speakers, Quarles (9:30 a.m. ET) and Barkin (1:00 p.m. ET) but neither should move markets.
What’s in Today’s Report:
U.S. stock futures are bouncing with EU shares this morning as the outlook on trade improved modestly overnight.
China’s retaliatory tariff deadline of June 1st and Trump’s indecision on the next round of tariffs were received as incremental positives, helping risk assets rise this morning.
The German ZEW Survey, EU Industrial Production, and the NFIB Small Business Optimism Index did not offer any surprises and are largely being shrugged off by investors so far this morning.
Trade is obviously going to continue to dominate the headlines amid the recent resurgence of volatility but there is one economic report to watch today: Import & Export Prices (E: 0.7%, 0.6%) and one Fed speaker: George (12:45 p.m. ET).
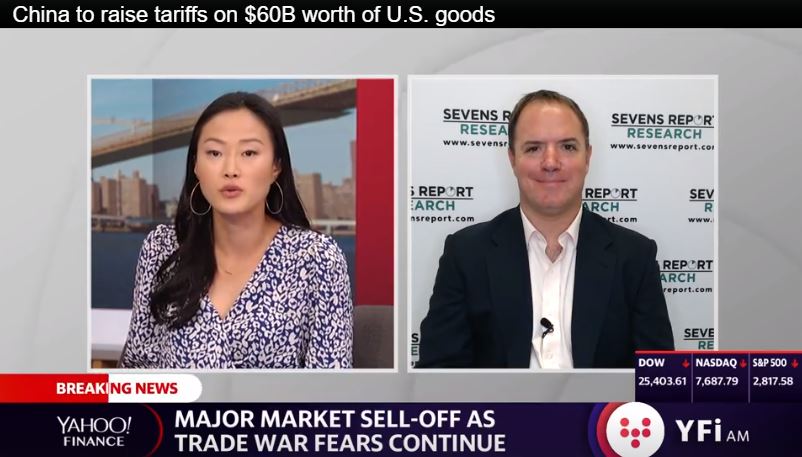
Tom Essaye interviewed with Yahoo Finance. A very timely chat on tariffs, fear within the market, what to expect with this market volatility and more…Watch the full interview here.
What’s in Today’s Report:
Futures are down more than 1% as markets digest the U.S./China trade situation.
Nothing specifically bad happened over the weekend on U.S./China trade, but Friday’s talks ended without a clear next step and that’s weighing on markets.
Additionally, Friday’s afternoon rally came despite any concrete, positive catalyst, so we are seeing those gains reversed and then some.
There are no economic reports today and just two Fed speakers, Rosengren (9:05 a.m. ET) and Clarida (9;10 a.m. ET), and neither should reveal anything new.
So, focus will be on the trade headlines and tea leaves. Anything that points to a specific next step (a date or event) in the U.S./China trade negotiation should help stocks rebound, while a continued lack of a concrete next step will increase market anxiety the longer it goes on.
What’s in Today’s Report:
Futures are marginally weaker as the U.S. increased tariffs on Chinese imports, as expected.
Positively, the trade talks will continue today, and the consensus market outlook remains that a deal does get done, likely in the next few weeks.
Away from trade, economic data was solid. Japanese Household Spending, British GDP and UK Industrial Production all beat estimates.
Today most of us will spend the day watching for any trade related headlines, and there are likely to be plenty. But, barring a total breakdown in negotiations, trade shouldn’t be too big of a negative on markets today.
Away from trade, we also get the most important economic data point of the week: CPI (E: 0.4%). PPI was more firm than it seemed, and if CPI is also firm then that will reduce the possibility of a preventative Fed rate cut, which will be another headwind on stocks. Finally, there are multiple Fed speakers today: Brainard (8:30 a.m. ET), Bostic (9:05 a.m. ET), Williams (10:00 a.m. ET) but none should move markets.
Tom Essaye Quoted in CNBC on May 9, 2019. “Small caps are most sensitive to overall economic growth. I think small caps are declining because…” Click here to read the full CNBC article.