Posts

Why High Yields Haven’t Caused a Bigger Pullback (Yet)

What’s in Today’s Report:

  • Why High Yields Haven’t Caused a Bigger Pullback (Yet)
  • Weekly Market Preview: Geopolitics and Fed in Focus (How many rate hikes?)
  • Weekly Economic Cheat Sheet: Can We Get More Goldilocks Data?

Futures are slightly lower following mixed geopolitical news over the weekend.

Starting with the geopolitical positives, there were reports that oil exports from the Middle East surpassed pre-war levels. Negatively, there was another unconfirmed attack on the Saudi East-West pipeline and increased fighting between Saudi Arabia and the Houthis. The net result is Brent Crude is modestly higher (up less than 1%).

Economically, the composite PMIs were solid as the EU PMI met expectations while the UK reading beat (52.0 vs. (E) 51.7.)

Today we get the final of the “Big Three” monthly economic reports via the ISM Services Index (E: 55.0) and the price index here will be key. The smaller the increase (or larger the decrease), the better for stocks as it pushes back on inflation concerns (and should push yields lower).
 

When Do High Yields Become a Bearish Gamechanger? Indicator to Watch

What’s in Today’s Report:

  • When Do High Yields Become a Bearish Gamechanger?  Indicator to Watch.

Futures are little changed following a generally quiet night of news as investor focus turns towards economic data.

Geopolitically, U.S./Iran negotiations yielded no material progress although increased oil exports from the region are keeping the rise in oil modest (up 1% overnight).

Economically, Chinese September PMIs met expectations.

The important economic data for this week really begins today and continues through Friday and the key for markets is Goldilocks data that implies solid growth but doesn’t raise rate hike expectations.

Today, important reports to watch are (in order of importance): Core PCE Price Index (E: 0.3% m/m, 3.2% y/y), ADP Employment Report (E: 70K) and, to a lessor extend, Final Q2 GDP (E: 1.5%).

Regarding the Fed, the parade of speakers continues this week and the less hawkish they are, the better for stocks.  Speakers today include: Barkin, (1:30 p.m. ET), Cook (3:25 p.m. ET), Goolsbee (5:10 p.m. ET) and Kashkari (6:00 p.m. ET).

Finally, earnings matter today with a key report from Micron (MU ($31.35) and the stronger the demand, the better.


Tom Essaye Quoted in Barron’s on August 3rd, 2023

Treasury Yields Keep Climbing

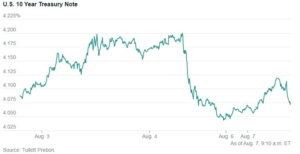
“The stronger-than-expected ADP jobs report pushed the dollar and long-dated Treasury yields higher on Wednesday, as the bond market continues to price in more resilient growth and/or inflation,” Tom Essaye, founder of the Sevens Report, wrote Thursday.

Click here to read the full article.